


 PDF Version
Knight Service
Our F2 valid cram we produced is featured by its high efficiency and good service. We are online for 24 hours. If you have any questions, just contact us without hesitation. We provide pre-trying experience, which means you can have a try before you buy it. Our F2 prep practice is well received. Most of the people who have bought our products have passed the exam and get the certificate.
Our F2 study materials have worked hard to provide better user experience. We promise that our content is up to date and once there is a new content, we will update it immediately. We will be responsible for our F2 training materials until you have passed the exam. What you need to do is to prepare for the exam and not concern with anything else.
There has been a dramatic increase in employee in the field, with many studies projecting that the unemployment rate in this industry is increasing. I don't know whether you are the one in the tide of job losses, if you are a member of the unemployed, you have to think about improving yourself. You should prepare your CIMA F2 actual test to make sure that you will not be replaced if you are a practitioner. Maybe you are too busy to prepare the F2 actual test. Our F2 pass4sure vce will help you solve the problem. Our F2 training materials are created by professional writer which are more secure than other enterprises.

Different versions to be chosen
In order follow the trend of the times, Our F2 study guide offers the PDF version to you. F2 PDF files can bring you many benefits. It occupies little memory and is easy to store. The important part is that it can be printed and you can read it at any time. PDF version won't have garbled content and the wrong words. Except for this version, Our CIMA Management F2 Latest Torrent also provides online practice. It will be very convenient if you could access the Internet. We have app which has pretty features, you can download after you have bought. What's more, our F2 training torrent is quite similar to the real exam circumstance; you can experience the exam in advance.
High passing rate
Our F2 training materials are popular because of high quality. People who have made use of our CIMA Management training materials will have more possibility to get the certificate. The content is written by professions who have studied the exam for many years. When it comes to service and passing rate, our F2 prep practice is sure to win out over those of our competitors. Compared with other companies, our F2 : Advanced Financial Reporting training materials carries a guarantee for the exam content. We will be responsible for our F2 valid questions which means the content will continue to update until you have passed the exam. We have a variety of versions for you to choose which can meet all kinds of requirements; you can choose a suitable one.
Instant Download: Upon successful payment, Our systems will automatically send the product you have purchased to your mailbox by email. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
CIMA F2 Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Analysing Financial Statements | 15% | - Impact of accounting policies - Ratio analysis and interpretation - Limitations of financial analysis |
| Topic 2: Financial Reporting Standards | 25% | - IFRS framework and application - Revenue recognition (IFRS 15) - Leases (IFRS 16) - Financial instruments (IFRS 9) |
| Topic 3: Integrated Reporting | 10% | - Sustainability and non-financial disclosures - Integrated reporting framework |
| Topic 4: Group Accounts | 35% | - Consolidated financial statements - Goodwill and non-controlling interest - Associates and joint ventures - Foreign currency consolidation |
| Topic 5: Financing Capital Projects | 15% | - Sources of long-term finance - Cost of capital calculations - Capital structure theories |
CIMA Advanced Financial Reporting Sample Questions:
Question #1
PQ is a retail business. In recent years they have improved their financial performance and increased their revenue. The following ratios have been calculated for the years ended 31 December 20X4 and
20X3: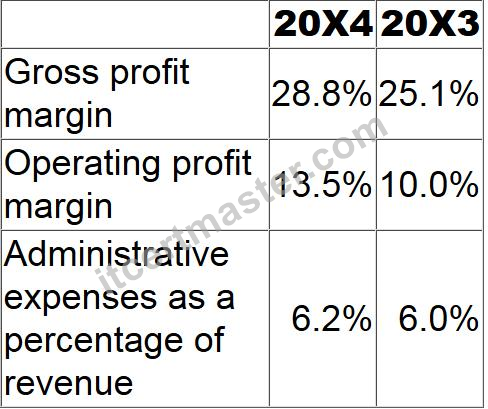
Which of the following explanations of PQ's financial performance is consistent with these ratios?
A. In 20X4 PQ reduced the unit selling price resulting in an increase in volumes sold and an increase in overall revenue.
B. PQ changed suppliers early in 20X4 because the new supplier agreed to supply the same goods at a cheaper price.
C. In 20X4 PQ sold a retail outlet resulting in a significant gain on disposal which has been deducted from administrative expenses.
D. In 20X4 taxation legislation was amended which reduced the rate of corporate income tax by 3.5%.
Question #2
When accounting for a finance lease under IAS 17 Leases, which TWO of the following are recognised in the statement of profit or loss?
A. Capital repayment element of the lease payments
B. Depreciation of the leased asset
C. Finance cost element of the lease payments
D. Lease payments paid
E. Lease payments payable
Question #3
Information from the financial statements of an entity for the year to 31 December 20X5: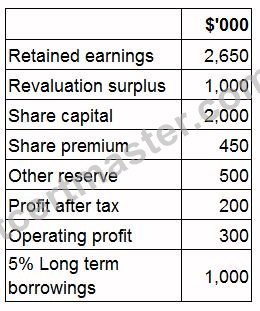
The gearing ratio calculated as debt/equity and interest cover are:
A. gearing of 15% and interest cover of 6.
B. gearing of 15% and interest cover of 4.
C. gearing of 16% and interest cover of 4.
D. gearing of 16% and interest cover of 6.
Question #4
AB acquired an investment in a debt instrument on 1 January 20X5 at its nominal value of $25,000, which it intends to hold until maturity. The instrument carried a fixed coupon interest rate of 5%, payable in arrears. Transactions costs of $5,000 were paid in respect of this investment. The effective interest rate applicable to this instrument was estimated at 9%.
Calculate the value of this investment that AB will include in its statement of financial position at 31 December 20X5.
Give your answer to the nearest whole number.
$ ?
Question #5
Which of the following would cause a deferred tax balance to be included in the statement of financial position for an entity?
A. The acquisition of plant and equipment a year ago where the tax depreciation rate is different to the accounting depreciation rate.
B. The acquisition of land for which there is no tax depreciation.
C. Impairment of goodwill that arose on the acquisition of a subsidiary entity.
D. Expenses in the statement of profit or loss which are not allowable for tax creating a permanent difference.
Solutions:
| Question #1 Correct Answer: B | Question #2 Correct Answer: B,C | Question #3 Correct Answer: A | Question #4 Correct Answer: Only visible for members | Question #5 Correct Answer: A |
 1400 Customer Reviews


